
Compare trust instruments and estate-review notes locally
Trace distribution standards, amendments, and memo assertions through a fictional trust pack, with a source table for qualified legal and tax review.
Separate the trust instrument, any modification, and the reviewer’s notes before asking how they relate. Document search can locate a distribution standard or appointment clause; it cannot determine the validity of a modification or calculate a beneficiary’s tax position.
The question this exercise answers
The Sterling exercise contains a fictional trust, modification agreement, and fiduciary memo. Start with the instruments, then use the memo to identify questions requiring further records and professional interpretation.
Download the fictional records
Download the separate records as a ZIP, extract it, and import the TXT files individually:
- Record 1: The sterling 1994 irrevocable dynasty trust (excerpt)
- Record 2: Agreement of modification and decanting under 12 del. c. § 3528
- Record 3: Confidential fiduciary audit memorandum & schedule b assets
The combined reading copy remains available. Import either the separate files or the combined copy, not both. Question Scope selects whole imported Documents; headings such as “Record 1” inside a single TXT file cannot be selected independently. Use the separate files for this walkthrough.
These are fictional teaching records, including any future dates, statute references, and professional opinions. They are not authentic filings, standards, advice, or a benchmark of OriginPage’s answer quality.
Locate the passages before asking for a comparison
Create a separate Workspace for the exercise. Import the individual records and wait for each to show Ready. Open Document details and check the retained text. These TXT exercises do not demonstrate PDF layout extraction or OCR.
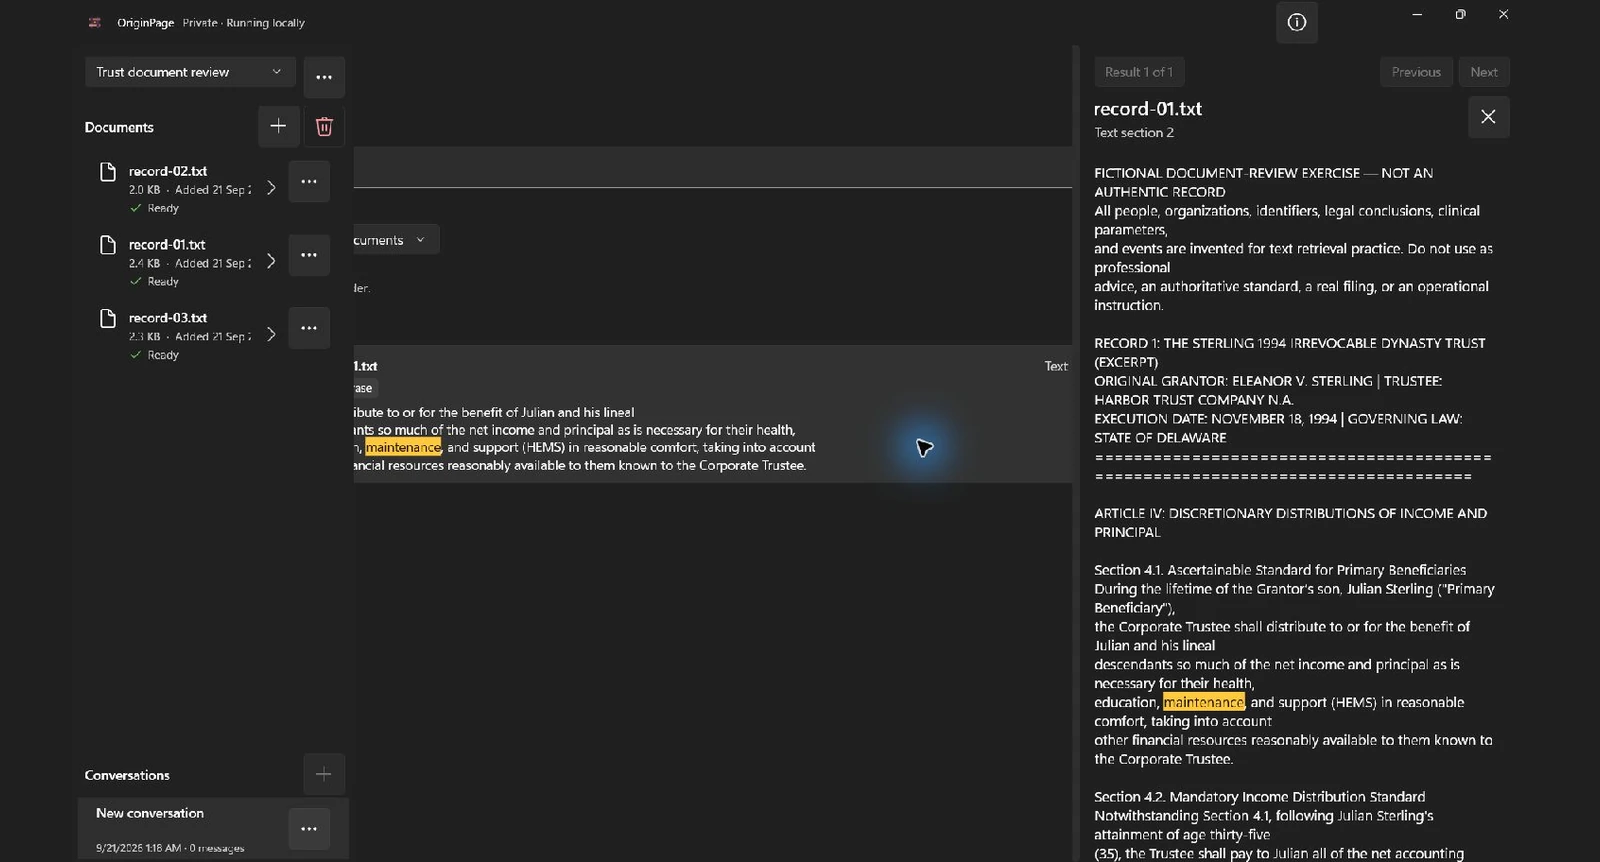
In Search, try maintenance in Exact phrase mode, without adding quotation marks. Search each relevant file as well as the collection. If wording differs, try Keyword or Hybrid and inspect the returned passages. A missing result is a reason to check wording, scope, and extraction—not proof of absence.
Choose the records allowed to answer
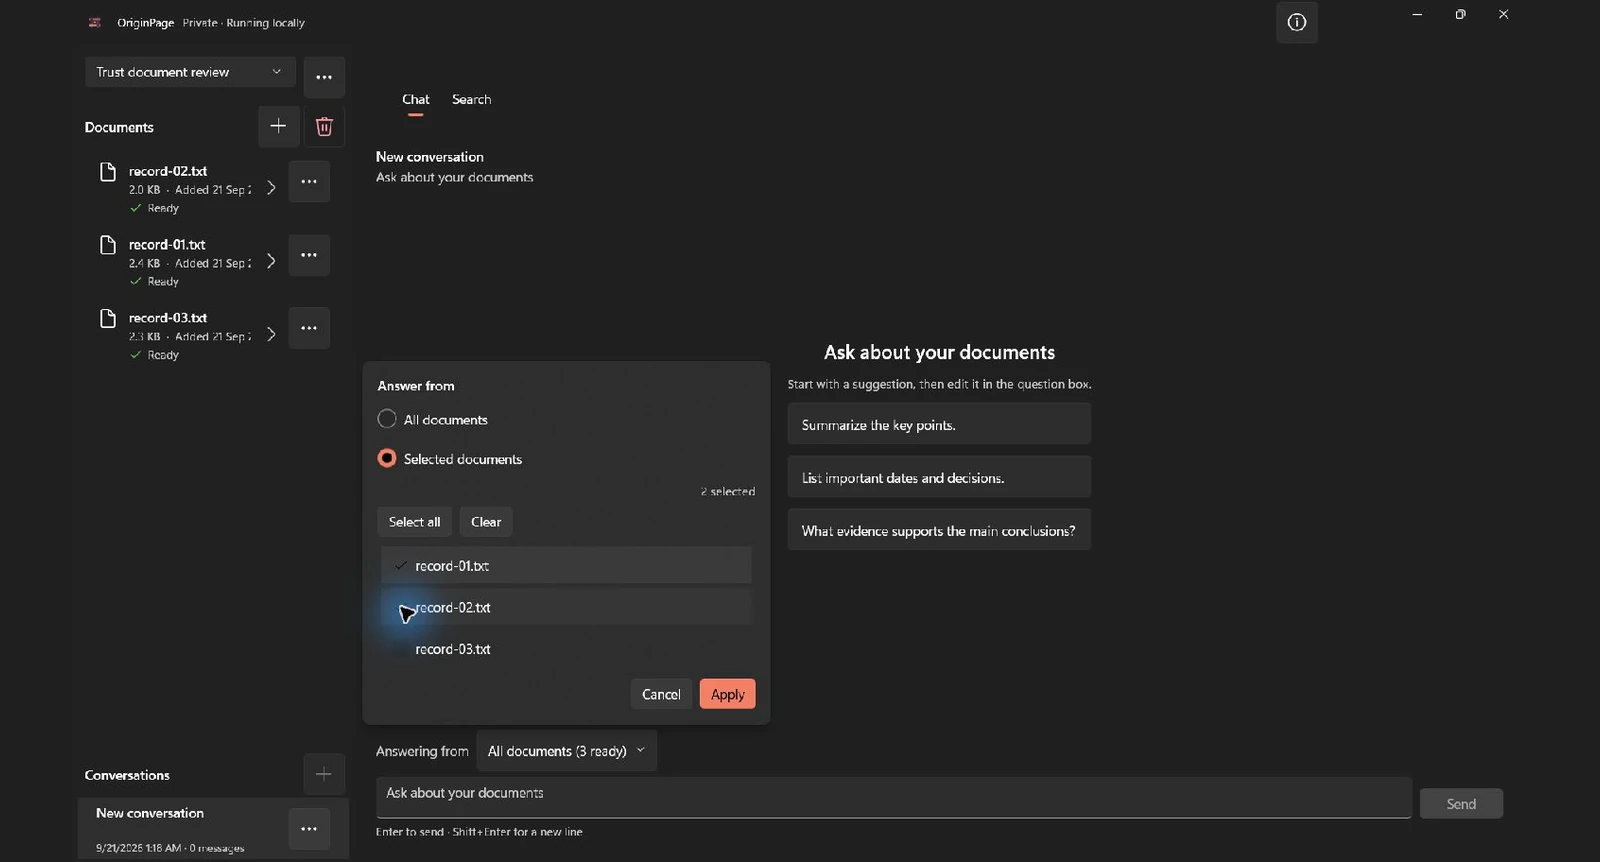
Select record-01.txt and record-02.txt for the instrument comparison. Add record-03.txt for a separate review of the memo’s assertions. In Chat, use Answering from → Selected documents. Search filters and Question Scope are separate controls; setting one does not set the other.
Try this focused question:
Compare the distribution standard and powers described in the trust and modification agreement. Cite the wording in each. Identify changes and missing authority without deciding tax treatment, validity, or fiduciary breach.
Check the result against the source
The following is an editorial answer key derived from the fictional files, not a recorded model response. Answers may omit relevant evidence; use Direct Search and the original records to complete the review.
| Topic | Review approach |
|---|---|
| Distribution standard | Locate the health, education, maintenance, and support language and compare the modification. |
| Appointment powers | Preserve who holds the power and the permitted recipients; do not reduce this to “broad discretion.” |
| Tax assertions | Attribute any inclusion-ratio or reporting conclusion to the memo and request the underlying returns and allocation records. |
A memorandum is not a tax return or proof that an election was made. The example’s statute references and tax opinions are fictional assertions for document review, not statements of current law. Do not infer a complete asset schedule from excerpts.
Keep a review record
Create an issue list with instrument date, clause, beneficiary or power holder, purported change, source of authority, missing record, and assigned professional. Keep conclusions provisional until the full file has been reviewed.
When a question needs two sides, open evidence from both. Check the filename, retained passage, surrounding conditions, and the original source where layout matters. A saved citation supports inspection; it does not certify the source or the conclusion.
Processing and professional boundaries
Use an approved device and matter-specific access and retention procedures for private-client records. Local storage does not by itself preserve privilege, satisfy fiduciary duties, or encrypt the data.
OriginPage processes supported documents locally during ordinary use. The privacy statement explains the limits, including Windows services and local account access. For formats and supported behavior, see what OriginPage supports.
Method
Revised September 21, 2026. The two screenshots show the downloadable fictional records imported separately into the locally installed OriginPage 1.0.35.0 candidate. We ran the stated Exact phrase query, opened the shown source passage, and applied the illustrated Selected documents scope. These captures demonstrate retrieval and scope, not generated-answer quality or professional validation. The source inspector clips part of the main pane in this candidate; the screenshots preserve that observed layout. The exercise findings are an editorial answer key, not a captured model response.